Wise Review 2026 – Is It the Best Multi-Currency Account for You?

Wise (formerly TransferWise) is a widely used multi-currency payment service for world travelers and people who need to transfer money across borders and currencies. Known for its transparent fee structure and competitive exchange rates, Wise’s streamlined platform appeals particularly to freelancers working with international clients, digital nomads hopping between countries, businesses engaged in global commerce, and frequent travelers tired of exorbitant foreign transaction fees. Wise’s core promise centers on simplifying international finance through user-friendly services that make sending, receiving, and holding multiple currencies both affordable and straightforward. Is Wise the best option for managing multiple currencies? Let’s take a deep dive into its features, fees, pros, and cons to help you determine if it’s the right financial solution for your international money needs.
Wise Bank Account Review: What Is Wise?
History & Background
Founded in 2011 by Estonian entrepreneurs Kristo Käärmann and Taavet Hinrikus, Wise rebranded from TransferWise in 2021. Its focus remains international payments and multi-currency money management. This review assesses the account for travellers and remote workers, rather than treating a changing company valuation as evidence of customer value.
 In partnership with DNworld
Core Features
Unlike traditional banks, Wise operates without physical branches, focusing instead on digital-first financial services. Its peer-to-peer model initially revolutionized currency exchange by matching users exchanging money in opposite directions, bypassing traditional banking networks and their associated fees.
How It Works
Users can send money internationally, make money transfers, receive payments in multiple currencies, convert between currencies, and hold balances in a Wise multi-currency account. Transfers typically process through local banking networks rather than expensive SWIFT systems, reducing costs significantly and supporting international money transfers at a lower cost than traditional cross-border routes.
Who It’s For
Wise serves individuals and businesses needing efficient cross-border financial services, particularly freelancers, digital nomads, international businesses, expats, and frequent travelers.
Key Features of Wise
Multi-Currency Support
Wise offers remarkable currency flexibility with support for holding balances in 40 currencies and sending money to 150 countries and territories. Users can keep one balance, switch into a different currency when needed, and convert into other currencies as plans change. This extensive network allows users to operate globally without maintaining multiple bank accounts across different countries.
Exchange Rates & Fees
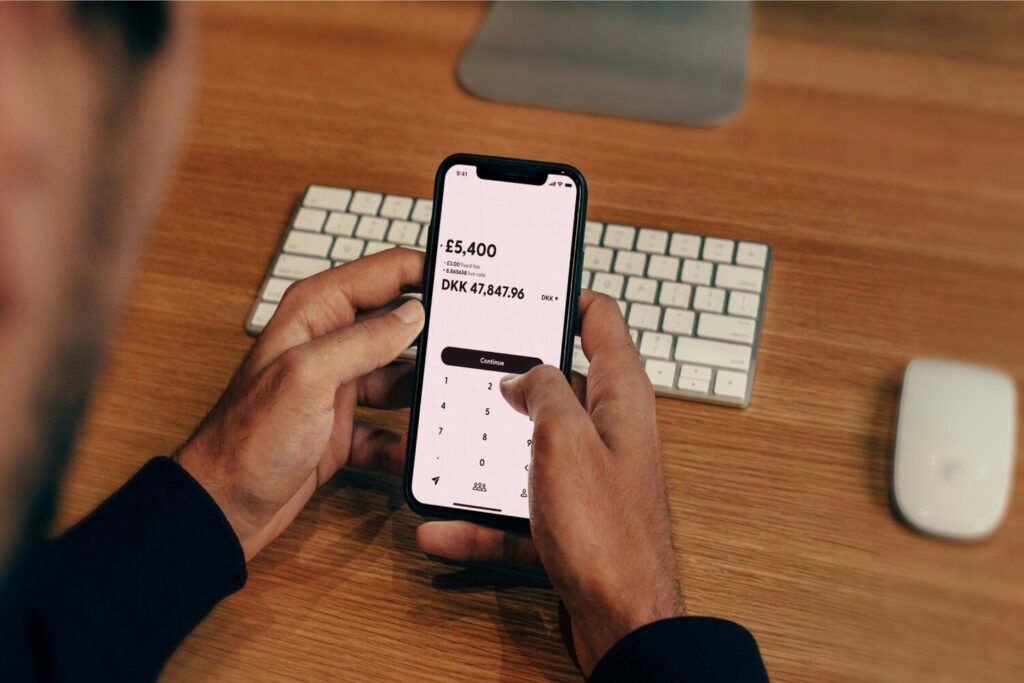
Wise uses the mid market rate and applies a separately disclosed upfront fee plus any relevant variable fee depending on the route. The amount depends on the currencies, payment method and transfer size. Compare the full Wise offer for your route, especially for popular currency pairs versus less common routes in certain currencies. A headline starting rate is not a quote for your transaction: compare the final amount your recipient will receive before confirming, since Wise charges can differ by payment route and transfer setup. See Wise’s current UK pricing; select your own country for the applicable schedule.
International Transfers
Delivery time depends on the payment route, funding method, receiving bank and any verification checks. Timing and pricing usually matter more when sending a large sum than with smaller transactions. Use the estimate shown for your actual transfer. Avoid relying on an instant-transfer claim when paying a time-sensitive deposit, and keep sufficient funds in another accessible account while a payment is being checked.
Account Management
Wise offers a highly intuitive web interface and mobile app (iOS and Android) with consistent high ratings. The platform provides comprehensive account management features including spending analytics, instant notifications, easy currency conversion, and support for direct debits where available in your region. Eligible cards and devices can also be used with Apple Pay and Google Pay. Customer support is available through multiple channels including chat, email, and phone, though response times can vary during peak periods.
Security & Regulation
Wise is a regulated payments provider overseen by the Financial Conduct Authority in the UK, with other regulators applying depending on the entity and country, but a Wise balance is not automatically the same as a bank deposit. UK electronic-money balances are safeguarded rather than covered by ordinary FSCS bank-deposit protection. Customer funds are held under safeguarding rules, typically in segregated accounts in most countries where the relevant entity operates. Rules differ by product and country. Two-factor authentication helps protect access, but it does not remove transfer mistakes or fraud risks. Read Wise’s explanation of safeguarding and deposit protection and the terms for your account location. Safeguarding and bank-deposit protection should be compared as different arrangements.
Fees & Costs
Account Fees
Personal registration is set up as a standard account, and holding supported balances does not carry a monthly subscription fee. Card issuance, conversions and some incoming payments can cost extra. Business-account setup and account-details charges have their own country-specific schedule; do not assume personal-account pricing applies to a company.
Currency Conversion Fees
Conversion fees are quoted before you exchange or send money as part of Wise’s transparent pricing. For a freelancer receiving income in one currency and paying rent in another, compare the complete route: receiving charges, conversion fees and any cost to move funds to a local bank, since costs can vary more in certain currencies than on major routes. A percentage alone can hide the practical effect of fixed minimum charges on small payments.
Withdrawal & Deposit Fees
For the UK pricing schedule checked on 14 September 2026, Wise lists £250 of cash withdrawals per month fee free up to that limit before its own withdrawal charge applies, followed by 2.69% on the amount above that allowance. ATM owners may add their own charges. The Wise debit card can still incur extra costs from third-party ATM operators or from conversion outside the allowance. Card-country and relocation rules matter, so check the limits shown in your app rather than applying this UK example worldwide.
Transaction Fees
Incoming payments are not universally free, so receiving money is not free across every route. Domestic payment routes in supported currencies may be free, while USD wires and some SWIFT receipts carry fixed charges. Check the payment instructions for your account details before invoicing a client, especially when a client may choose an international wire instead of a local transfer, since some providers avoid high fees better than banks but the payment type still matters.
Hidden Costs
Wise largely eliminates the hidden charges typical of traditional banks, though users should note potential fees for certain deposit methods and for exceeding ATM withdrawal limits. Additionally, receiving payments in certain less common currencies may incur small receiving fees.
Pros & Cons
Pros
Consistently offers mid-market exchange rates without hidden markups
Supports quick and cheap transfers for international payments
User-friendly platform with excellent mobile app
Supports 40 currencies and sends to 150 countries and territories
Account details for receiving supported currencies, subject to country and eligibility
Highly transparent fee structure
Strong for holding balances and making payments in other currencies without relying on bank exchange spreads
Regulated in multiple jurisdictions with strong security measures
Quick transfer processing times compared to traditional banks
Cons
Not available in all countries or territories
ATM withdrawal limits may be restrictive for high cash users
Customer service response times can vary during peak periods, and some negative reviews mention support delays or account checks
Some less common currencies not fully supported
Not a replacement for every bank service; investment or interest features vary by country and carry separate terms
Occasional verification delays for new accounts in certain regions; customer reviews are often positive overall, though complaints tend to cluster around delays and restrictions, so read recent reviews critically before opening an account
Check whether your accounting or payment workflow supports the required Wise integration
How to Open an Account
Opening a Wise account is straightforward and can be completed entirely online:
Visit the Wise website or download the mobile app
Register with your email, Google, Facebook, or Apple account
Verify your identity by providing your address, birth date, and uploading government-issued ID (passport, driver’s license, or national ID)
For some countries, you may need to upload proof of address (utility bill, bank statement)
Follow the funding and verification instructions shown for your country and the features you want to activate
Use the features shown as available after verification; some services may need additional checks
Verification time varies and additional documents may be required. Wait until your account and receiving details are available before directing salary or client payments to them. Business accounts require documentation about the company and its owners. Never send identity documents through an unsolicited message claiming to be support.
Who Should Use Wise?
Wise offers particular value for:
Digital Nomads & Remote Workers
Those working internationally while traveling may find Wise a good fit when they need to get paid and hold balances across borders without establishing bank accounts in each country.
Freelancers with International Clients
Receiving supported currencies can simplify client payments. Check receiving and conversion fees for the actual payment route.
Expats
Individuals living abroad who need to manage finances in both their home and resident countries find Wise’s multi-currency capabilities invaluable.
Small to Medium Businesses
Companies engaged in international trade appreciate Wise’s transparent fees and business-specific features like batch payments and accounting integrations.
Frequent Travelers
If you regularly visit multiple countries, Wise’s multi-currency debit card can help with spending money abroad in multiple currencies while offering significant savings on foreign transaction fees compared to traditional bank cards.
If you receive income in one currency but have expenses in another, or frequently transfer money internationally, Wise provides substantial cost savings and convenience over traditional banking options, especially when moving funds in one currency and paying expenses in a different currency.
Competitor Comparison
When compared to other multi-currency platforms:
Wise vs. Revolut – Compare the exact currency route, account tier, allowance and weekend conditions at the time of purchase. Wise’s separately quoted conversion fee makes costs easy to inspect; Revolut may suit someone who wants a broader set of app features. Neither should be declared cheaper for every transfer without a like-for-like quote.
Wise vs. Payoneer – Marketplace payout support, the currencies you receive and withdrawal costs are more useful comparison points than a blanket cheapest-provider claim. Check whether your client or marketplace supports the receiving details you intend to use.
Wise vs. PayPal – PayPal may be convenient when a buyer or merchant already uses it. For international transfers, compare the recipient’s net amount after both the exchange-rate margin and any transaction fees. Buyer protection and a bank-style transfer are different services, so choose for the actual payment purpose.
Wise vs. Traditional Banks – A bank may offer loans, cash services or deposit protection that a payments account does not. Compare its quoted recipient amount and delivery time with Wise. Keeping a local bank account alongside Wise can also provide a backup if a card is lost or verification temporarily restricts access.
For currency exchange and international transfers, Wise is worth comparing on total cost, delivery time and the features available in your country.
Conclusion: Is Wise Worth It?
Wise stands out for offering genuinely competitive exchange rates with transparent fees in an industry often characterized by hidden charges. Its strongest selling points include mid-market exchange rates, low transfer fees, and an intuitive user experience across multiple platforms.
For those regularly dealing with multiple currencies, Wise delivers exceptional value and convenience. Its ability to provide local bank details in major currencies eliminates the complexity of international banking for many users.
However, if you rarely make international transfers or need comprehensive banking services like loans, credit cards with rewards, or interest-bearing accounts, you might find Wise’s offerings limited compared to traditional banks or neobanks like Revolut.
The final verdict: If you need affordable, transparent international money management, Wise is a strong option to compare. However, if you prioritize all-in-one banking with additional financial products, consider complementing Wise with services from traditional banks or more comprehensive fintech alternatives.
Thinking of signing up? Check out their website and compare options before deciding, especially focusing on the specific currency pairs and features most relevant to your needs.
Wise bank account review: practical questions for digital nomads
Can Wise replace my main bank?
It can handle useful international payment tasks, but keep a backup for cash access, emergencies and services your Wise account does not provide. Check your country’s availability before assuming you can keep the same features after a move.
What should I compare before transferring?
Enter the same amount and destination with each provider. Compare the recipient’s final amount, estimated arrival, funding method and cancellation conditions. For rent or a property deposit, verify the recipient’s details through a trusted channel first.
How do I avoid unnecessary card conversion?
When a merchant or ATM offers to bill you in your home currency, compare that conversion with paying in the local currency. Save the receipt and review the transaction in the app. A low-fee travel card cannot prevent a separate ATM operator charge.
Pricing reviewed 14 September 2026. UK examples are identified above; fees and product availability depend on where your account is registered.
Responses